Blue Sweep...

BentinPartner Weekly

Dear Reader,
Please find below our latest Weekly Trend Report.
Have a nice start of the week.
Marc Bentin,
Bentinpartner GmbH
While the initial reaction to the announcement of the Blue Sweep victory was one of near panic on Tuesday night, triggering a swift and sharp 2.5% decline in Nasdaq futures (and a 4% drop in the Korean Kospi), the rapid recovery from the abyss in the Korean market, which erased its losses within a matter of minutes, found an immediate echo in US futures markets. They too reversed their initial negative reaction, setting the stage for a violent short squeeze in the opposite direction on Wednesday, triggering panic, this time among hedgers, who rushed to monetize whatever profits remained on positions established ahead of what was widely seen as a predictably market-unfriendly outcome, or at the very least an event whose probabilities were far from negligible.
This is what we wrote on Wednesday whilst noting that several sectors of the US stock market, were still bruised on Wednesday despite a counterintuitive major indices squeeze, notably the energy sector (on the assumption that D. Trump would be crippled enough not to further escalate the war in Iran) and precious metals sectors (on the assumption that if the Nasdaq rallies/squeezes… there is no need for protection with gold).
Then came Thursday and an epic reversal of the reversal that wiped out some USD2.5trn in US market cap value (the largest ever one day value loss ever) with the biggest victims being the tech and AI sector in particular. With most hedges taken out, stocks were ready for the real move, the one that would take into account the likely freeze of many data centers necessary to sustain the Ai buildout, optimism and whatever resilience was to be found on this equity sector after an already painful initial correction in July and a painful relapse in October.
The damage was real with chip stocks dropping -17% below their long term 200d moving average. According to closely followed analyst Harnett from BoA, a good entry level in the 1996 rout was …20%-25% below the 200dMA which he pointed out as a reason for optimism over the week end... Thursday also witnessed the biggest put buying day on record.
The next move could well be another squeeze not least because this Anthropic IPO needs to come out alive, sometimes this month at a valuation of USD1.5trn where it is being held on the balance sheet of many tech companies. As a result, going completely to cash or fully hedged and go away may not necessarily be the best option at this juncture, especially after the wash out that affected many sectors beyond tech, and even if a cautious wait and see attitude towards the Ai universe may still be justified. We would rather focus on building a “fortress” portfolio (there is admittedly no such thing over the near term) centered on strong balance sheets, solid positive “cash flows” and still defensive sectors.
In any case, we should also not underestimate the increased chances of a monetary pivot to follow last week’s political pivot and in a not-too-distant future even as expectations currently remain priced (at 78% on Friday) for another Fed hike in December in the US (and one in Europe) following recent disappointing inflation data and following last Friday’s stronger than expected US job report (+165k jobs created vs. 70k expected and 39k last with the unemployment rate dropping to 4.1% from 4.2%) which conveyed a similar message of job market resiliency than the private job survey (+85k vs. 66k expected) published on Wednesday and the Jolt job openings report (which rose to 7523k vs. 7164k expected and 7079k previously).
After everything was said and done last week, the semi-index dropped -12.2% (the largest loss since covid) with Micron -17% and Nvidia -9% and the Nasdaq100 -6.3%. Widespread losses were also reported among Hedge Funds across a variety of strategies with Goldman Sachs High Beta Momentum now down a whopping 50%, the largest drawdown since Goldman started the series.
In this context, bonds regained their status as a safe haven with 10Y US (and German) Treasury yields dropping -7bps. At the same time and despite renewed risk aversion French and Italian spread to Bunds declined by 14bps and 12bps respectively.
This did not prevent AI credit spreads to widen considerably last week (with CoreWeave yields on its 2032 bonds spiking to a record 16.42% on Friday while ORCL credit spread also spiked 30bps on the week (and 15bps on Friday) and while Meta spread climbed by 7bps over the past week as well.
The dollar index gained 0.4%, largely as a result of the strong US employment report on Friday which raised Fed tightening expectations.
At the beginning of the week, gold and bitcoin were neck to neck on their negative YTD performance but after last week’s developments, after Gold traded below $4’000, the real gold took the advantage again, outperforming digital gold by 8% which must have been reassuring to the purists and also related Central Banks having reportedly purchased gold this quarter at the fastest pace in 2 years despite downside pressure on prices, bringing their estimated purchase so far this year to 675 tons (and 321 tons in Q3), according to estimates of the World Gold Council.
However, commodities dropped sharply led by oil -12% decline (on some overrated Iran peace hopes…not even talks) while copper also dropped -3.4% (on reduced enthusiasm for the AI buildout).
Good luck for this week-
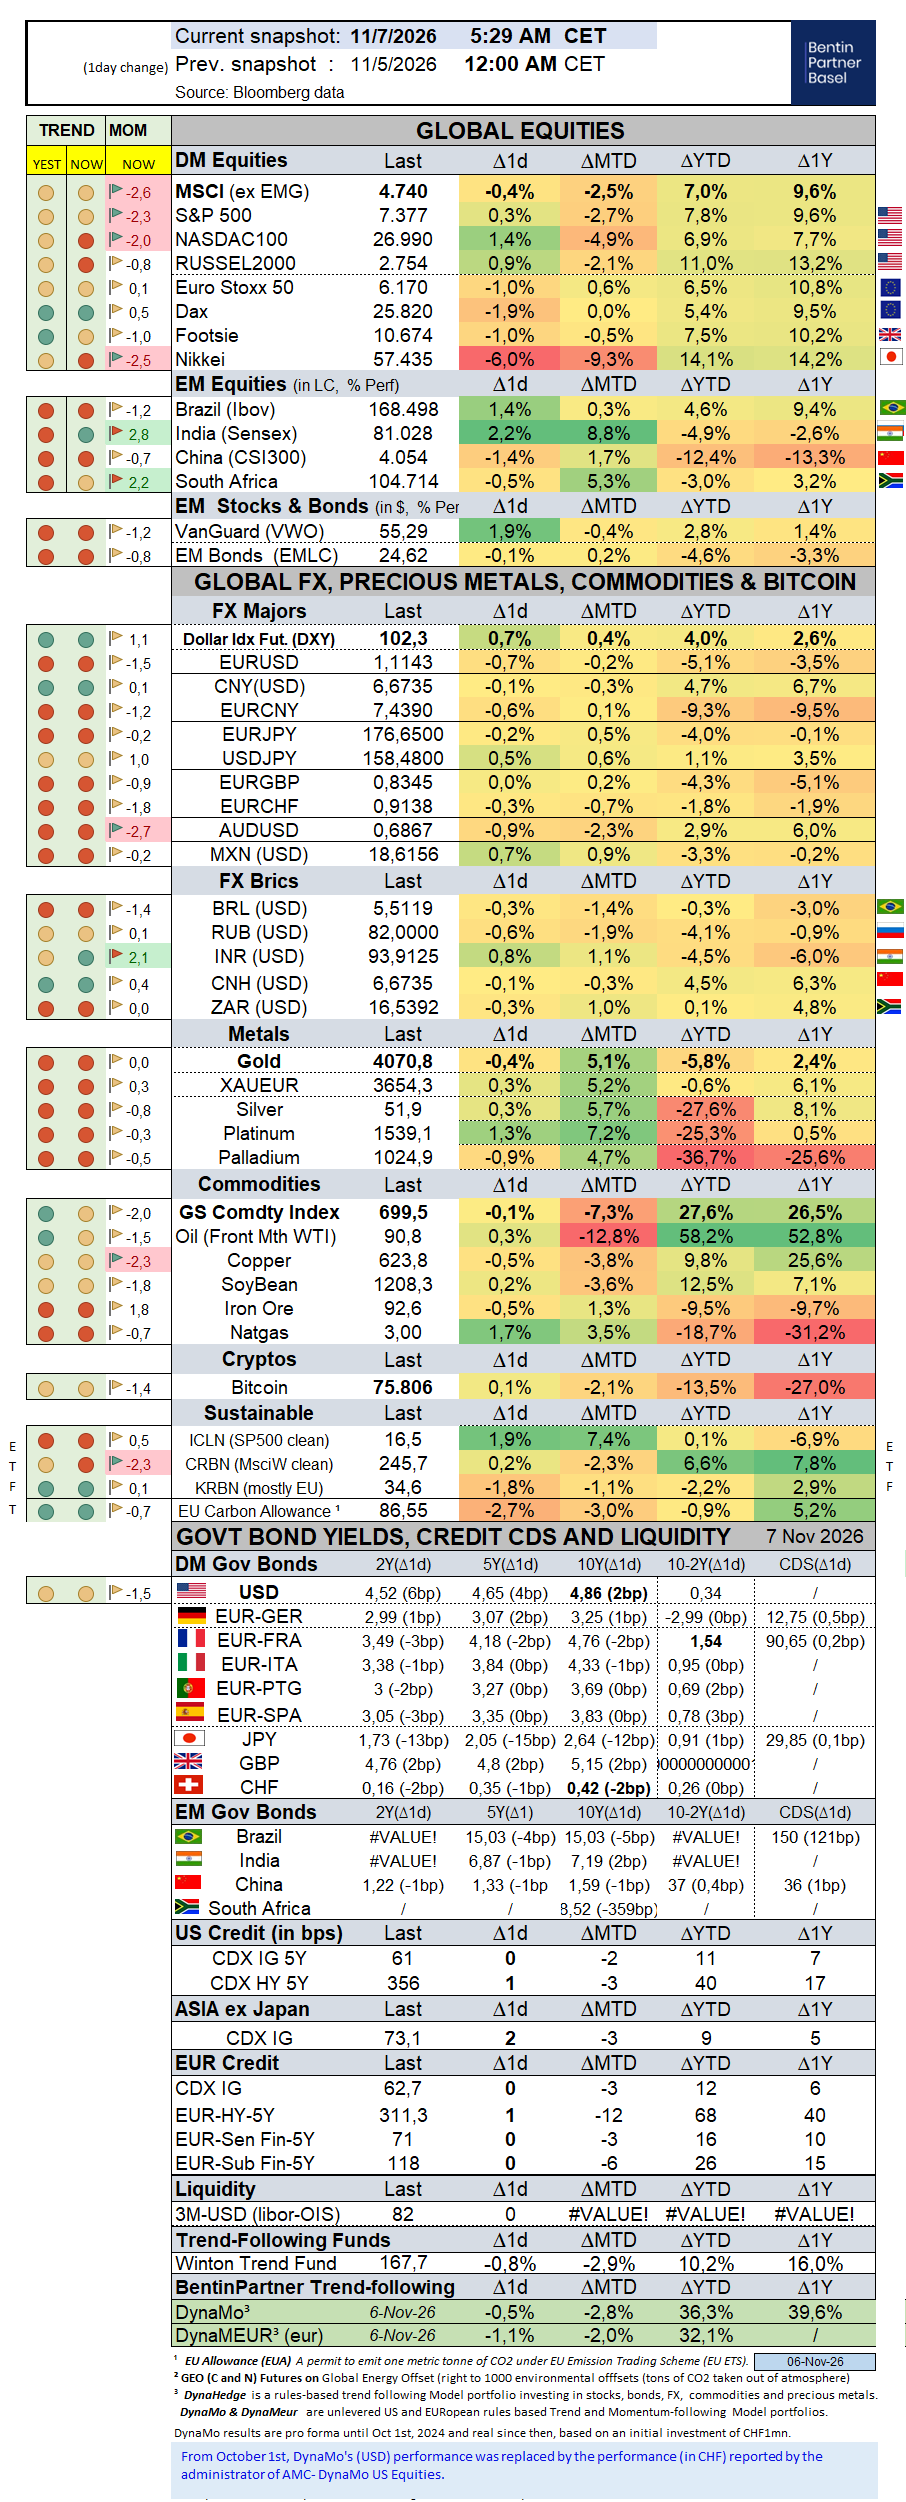
Over the past week, the S&P500 sold off by -2,7% (7,8% YTD, Z-score -2,4) while the Nasdaq100 sold off by -5,0% (6,8% YTD, Z-score -2,0). The US small cap index sold off by -2,0% (11,2% YTD). AAPL dropped -0,7% (25,9%).
The Equally Weighed SP500 dropped -1,0% (12,8% YTD), outperforming the S&P500 by 1,7%. The median SP500 YTD return closed the week at 9,0%.
Cboe Volatility Index rallied 32,0% (71,5% YTD, Z-score 2,1) to 25,64.
The Eurostoxx50 gained 0,7% (8,9%), outperforming the S&P500 by 3,4%.
Diversified EM equities (VWO) dropped -0,4% (2,8%), underperforming the S&P500 by2,3%.
The Dollar DXY Index (UUP) measuring the USD performance vs. other G7 currencies gained 0,4% (7,8%) while the MSCI EM currency index (measuring the performance of EM currencies vs. the USD) dropped -0,3% (3,5%).
10Y US Treasuries rallied -7bps (69bps) to 4,86%. 10Y Bunds dropped -7bps (40bps) to 3,25%. 10Y Italian BTPs rallied -19bps (78bps, Z-score -2,0) to 4,33%, outperforming Bunds by -12bps.
10Y French OAT's rallied -21bps (119bps) to 4,76%, outperforming Bunds by -14bps.
US High Yield (HY) Average Spread over Treasuries dropped -4bps (70bps) to 3,36%. US Investment Grade Average OAS climbed 1bps (18bps) to 1,02%.
In European credit markets, EUR 5Y Senior Financial Spread dropped -3bps (16bps) to 0,71%.
Gold rallied 5,1% (-5,8%) while Silver rallied 5,7% (-27,6%). Major Gold Mines (GDX) rallied 13,6% (2,1%).
Goldman Sachs Commodity Index sold off by -6,2% (41,1%). WTI Crude sold off by -12,8% (58,2%).
Overnight in Asia…
S&P future + 39 points; Hong Kong +0.2%; Nikkei+3%; China +0.2%
Nvidia CEO Jensen Huang admitted he had an affair with a woman identified in a series of reports as a suspected Chinese spy, plunging the chip colossus into a crisis like none before in its three-decade history, Bloomberg reported. “I was unfaithful to my wife,” Huang said in the memo. “My actions hurt her and our children. There is no excuse for what I did. I am deeply sorry.”
This incident was threatening to further roil an AI market shaken by concerns about a slowdown in data center spending, Bloomberg also reported. That said, it likely explained the Asian stocks rebound this morning with Taiwan rallying 5%, the most since July 31st, after local authorities “introduced measures to restore investor confidence”. These measures included Taiwan’s market regulator and finance ministry both pledging to impose curbs on short selling from today onwards, and a readiness to deploy $15.2 billion stock stabilization fund. They could easily be joined by other forces. The MSCI Asia Pacific Index jumped 2.5%.
President D. Trump said he was “only kidding” when he offered the job of White House Press Secretary to UFC chief Dana White.
Trump told reporters that White would be in Washington on Monday “for other reasons” and would “come over and see me.”

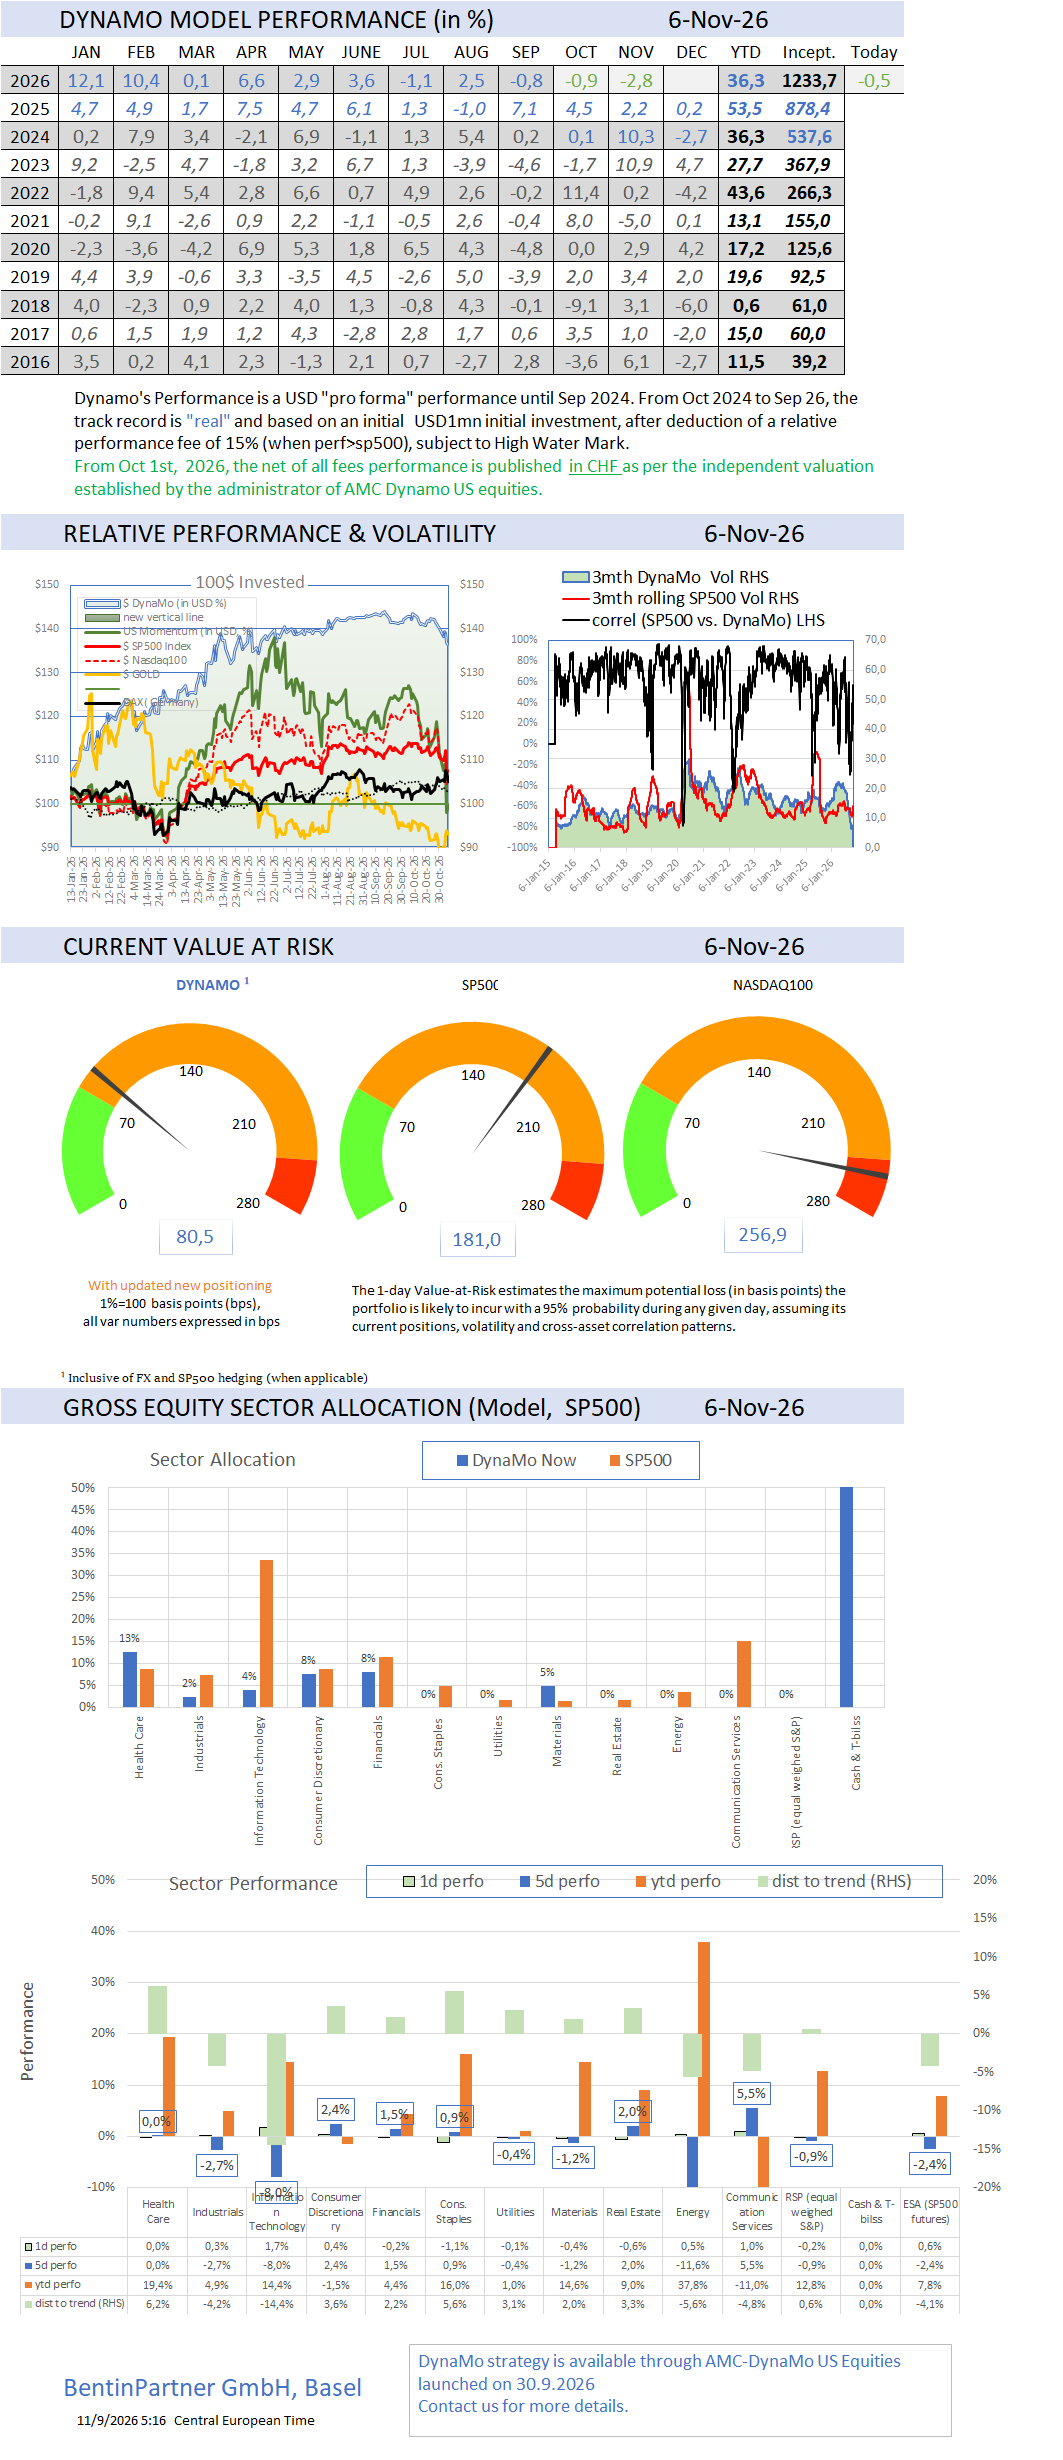
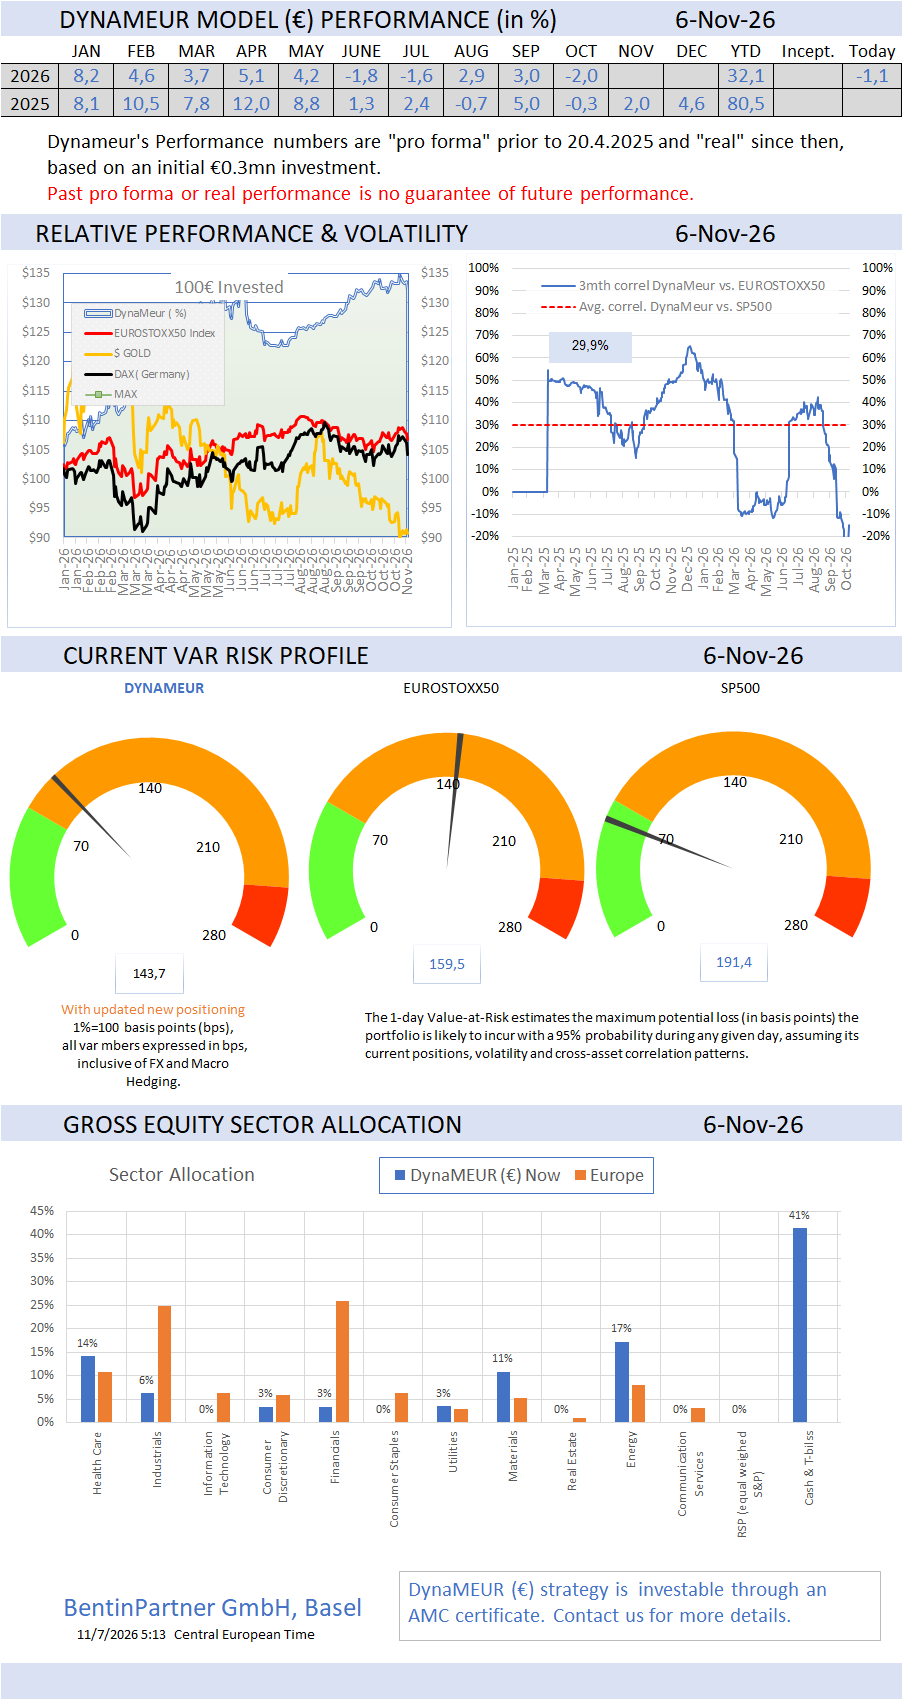
To learn more about our AMC offering and how to invest in the trend-following, visit our Advisory web page.
If you like our Weekly, you will love our Daily!
Consider a subscription today. Discounts may apply!
To learn more about us and how we can assist you, check our website
Important Disclaimer
© Copyright by BentinPartner LLC. This communication is provided for information purposes only and for the recipient's sole use. Please do not forward it without prior authorization. It is not intended as a recommendation, an offer, or solicitation for the purchase or sale of any security or underlying asset referenced herein or investment advice. Investors should seek financial advice regarding the suitability of any investment strategy based on their objectives, financial situation, investment horizon, and particular needs. This report does not include information tailored to any particular investor. It has been prepared without any regard to the specific investment objectives, financial situation, or particular needs of any person who receives this report. Accordingly, the opinions discussed in this report may not be suitable for all investors. You should not consider any of the content in this report as legal, tax, or financial advice. The data and analysis contained herein are provided "as is" and without warranty of any kind. BentinPartner LLC, its employees, or any third party shall not have any liability for any loss sustained by anyone who has relied on the information contained in any publication published by BentinPartner LLC. The content and views expressed in this report represent the opinions of Marc Bentin and should not be construed as a guarantee of performance with respect to any referenced sector. We remind you that past performance is not necessarily indicative of future results. Although BentinPartner LLC believes the information and content included in this report have been obtained from sources considered reliable, no representation or warranty, express or implied, is provided in relation to the accuracy, completeness, or reliability of such information. This Report is also not intended to be a complete statement or summary of the industries, markets, or developments referred to in the Report.

Comments