Morgan Stanley : "Go Max Overweight Global Stocks"...

BentinPartner Weekly

Dear Reader,
Please find below our latest Weekly Trend Report.
Have a nice start of the week.
Marc Bentin,
Bentinpartner GmbH
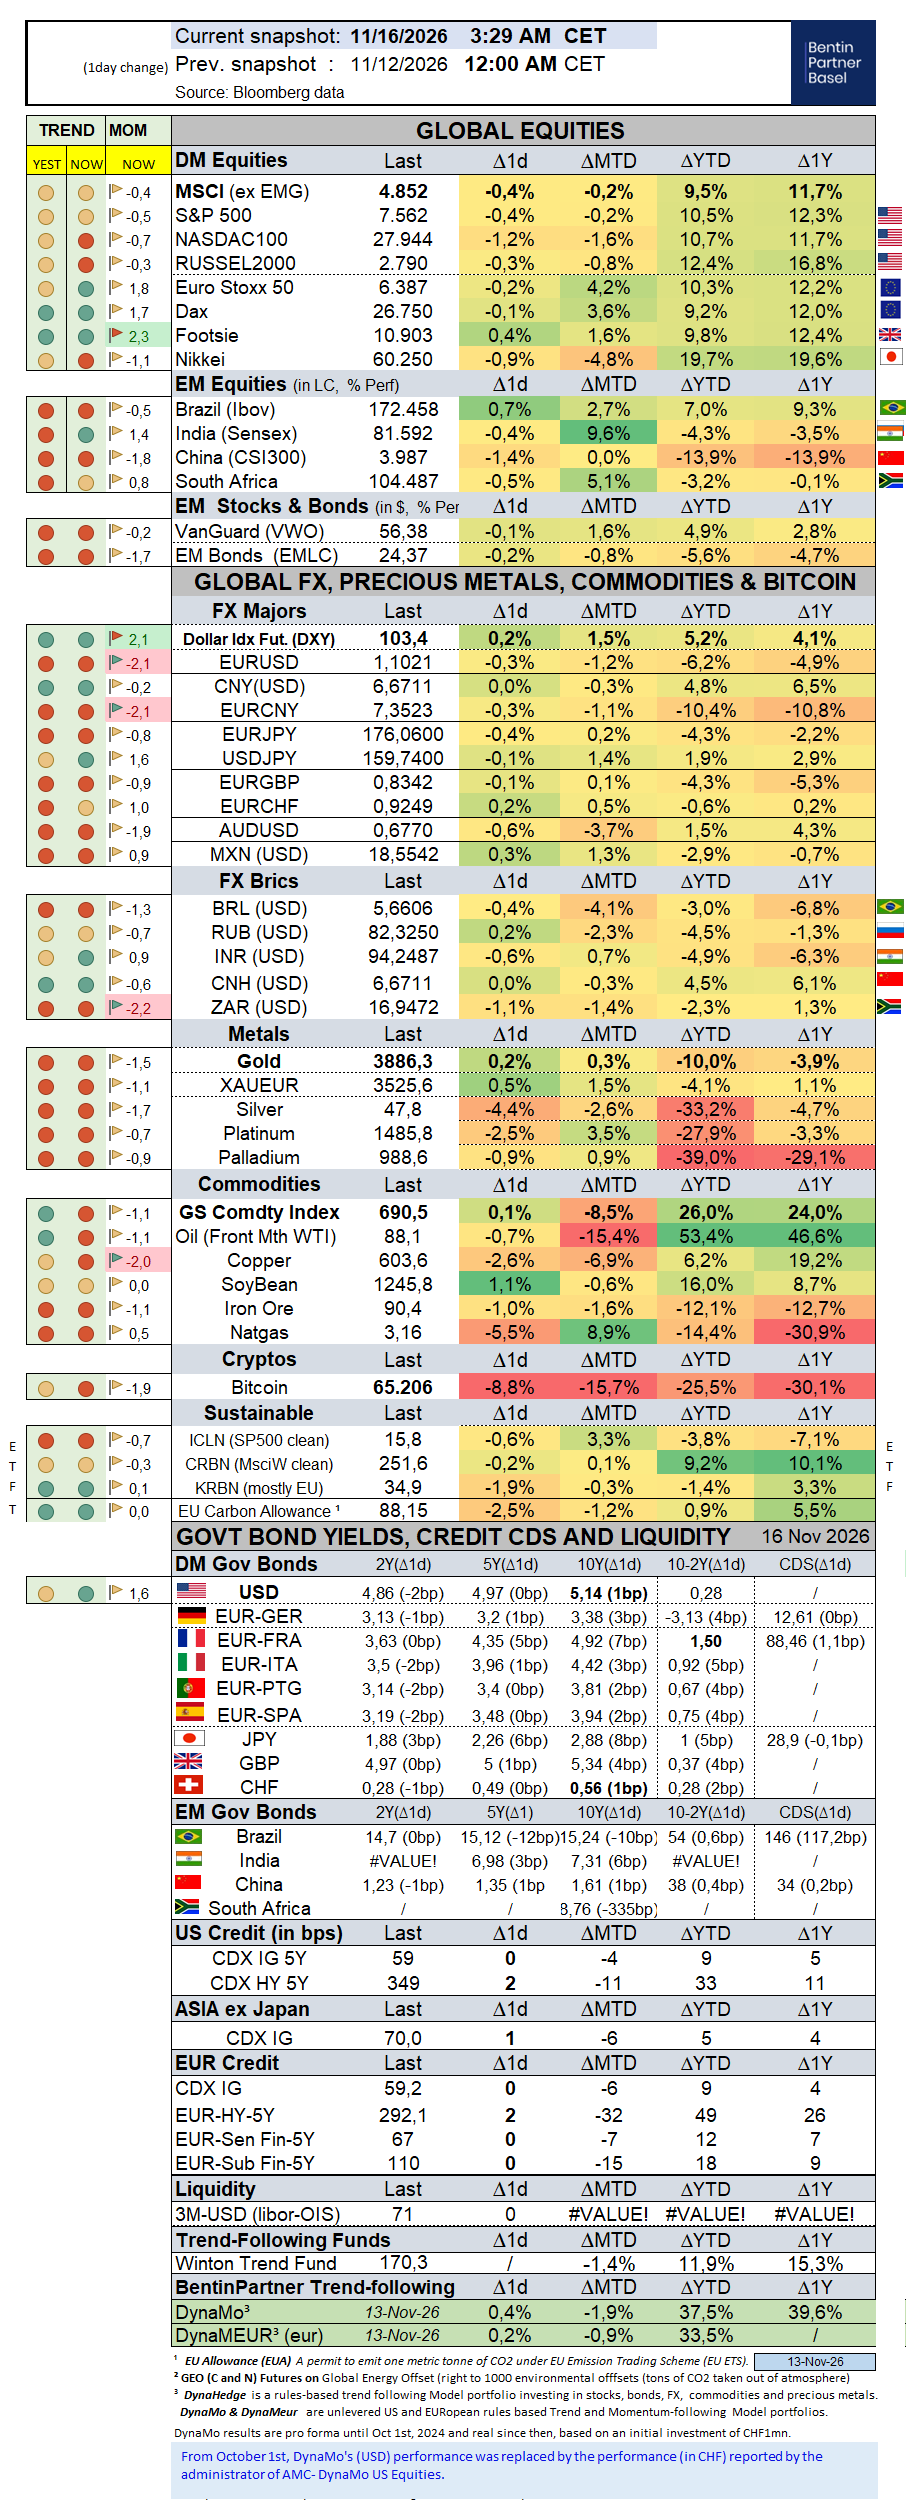
US stocks lived dangerously last week although the weekly snapshot suggests otherwise (in some ways) with most US indices posting additional gains for the week.
Monday started with a squeeze in the semi sector (+6.9%) that pushed the Nasdaq 3.4% higher. However, on Tuesday, the October CPI report came out surprisingly strong (+0.4% vs. 0.3% expected) which firmed up the likelihood of a December rate hike. Interestingly and even before the CPI report was released, Fed Governor Waller had warned that in the case of a strong CPI report (exceeding +0.3%), the Fed would likely tighten by 50bps rather than the 25bps but the market did not buy these expectations, ending the week with expectations for December still stuck at 25bps (only pricing 10% odds of a larger 50bps hike).
Stocks gyrated for the rest of the week, ending Friday on a softer note but most of the squeezy tech Monday gains managed to stick to the wall despite news that Nvidia CEO Jensen Huang was left with no other choice than to resign on Thursday following the revelation of a second adultery relationship.
Over the course of a summer meeting, he proceeded to tear into the woman who is now taking over for him as Nvidia CEO. Colette Kress was ‘a deer in the headlights,’ he said…at the time, according to a WSJ article. “ If powers that be (whoever that is, who at this stage, seems to be mostly US Treasury Secretary S. Bessent due to his anti-Chinese inclinations as no American argued harder for selling AI chips to China than Jensen Huang) need a third one, they will probably find one but fresh developments over this week end suggested that Wall Steet and Tech Titans are now on a war path to reinstate Jensen Huang in his function because of the appreciation that he is at the epicenter of the AI technological revolution and the architect and provider of funds for its (mostly circular) financing.
Most importantly, over the week end, E. Musk said he was supportive of reinstating him, adding that he would otherwise welcome all those engineers that would choose to defect from Nvidia following their key man risk boss ousting… Such a comeback would not be without precedent considering Sam Altman’s temporary firing from OpenAI in 2023.
AI without the perspective of Jensen Huang returning is probably too dangerous, three days before the long-awaited IPO of Anthropic that will mint a next generation of billionaires (and add a few billions to those who already are).
A success for this IPO is something Wall Street has diligently prepared for weeks and it cannot be underestimated the extent by which it holds the key to a continuation or halt of the US tech rally, at a time that is also, from a seasonality point of view, generally positive for stocks.
In this context, Morgan Stanley suggested over the week end to go “Max overweight” global stocks (admittedly a recommendation likely to be conflicted going into the IPO), citing an intact AI capital spending that should extend resilient economic and earnings growth into next year. Morgan Stanley also upgraded Japanese and European stocks, lifting its price target for the SP500 to a level implying 15% upside, Bloomberg noted.
On the economic side, applications for a mortgage to purchase a home rose 8% for the week but were 18% lower year over year while existing US homes slumped in October to their slowest pace in more than 16 years as mortgage rates rose sharply. At the same time, sellers are still digging in, refusing to cut prices, implying that September’s frozen housing market became October’s frozen market as well.
That said, the bond markets saw it otherwise and US Treasury yields climbed back up to 5.15% (+11bps), taking Fed speak (and supply) more seriously. Japan’s 10Y JGB yields surged 22 bps to 2.87% (+81bps ytd) while in Europe 10Y Bunds yields added 12 bps to 3.38% (+52bps ytd) with French OAT’s climbing 16 bps to 4.92% (+136bps ytd), and underperforming Bunds by 4 bps.
While credit spreads narrowed last week, Anthropic shouldn’t count on J. Gundlach buying into its inevitable debt issuances to support its AI future. ‘I wouldn’t touch it,’ the DoubleLine founder said…
Elsewhere, Fitch placed Paraguay’s credit rating on watch for a potential downgrade…, citing risks to the nation’s finances and economy from a banking crisis that toppled President Santiago Peña.
In last week context which saw further stock and debt flows (and absorbed supply) into tech, the USD extended its recent powerful rally and the dollar index gained 1.3% on the week (+ 5.5% ytd).
The combination of higher yields, a higher dollar and higher stocks were not supportive of precious metals which closed the week at or near their recent lows (with bitcoin faring much worse). They will recover strongly at some point but this will likely take a more tepid than expected tightening by the Fed in addition to expected continued Central bank buying.
Elsewhere in Geopolitics, President Trump said… the U.S. didn’t need a deal with Iran and would prefer Vice President JD Vance, who has taken the lead in negotiations, work on investigating American cities run by Democrats.
Also, on the Russia/Ukraine war, recent talks with US mediation in Abu Dhabi produced a meaningful humanitarian result (the prisoner-exchange deal) and kept negotiations alive, but the core issues of territory, security arrangements, and a ceasefire remained unresolved.
Over the past week, the S&P500 rallied 2,6% (10,6% YTD) while the Nasdaq100 rallied 3,6% (10,7% YTD). The US small cap index gained 1,4% (12,7% YTD). AAPL rallied 4,1% (31,0%).
The Equally Weighed SP500 rallied 2,4% (15,5% YTD), underperforming the S&P500 by-0,2%. The median SP500 YTD return closed the week at 11,7%.
Cboe Volatility Index sold off by -24,7% (29,1% YTD) to 19,3.
The Eurostoxx50 rallied 3,6% (12,8%), outperforming the S&P500 by 1%.
Diversified EM equities (VWO) gained 2,0% (4,9%), underperforming the S&P500 by-0,6%.
The Dollar DXY Index (UUP) measuring the USD performance vs. other G7 currencies gained 1,3% (9,1%, Z-score 2,6) while the MSCI EM currency index (measuring the performance of EM currencies vs. the USD) dropped 0,0% (3,5%).
10Y US Treasuries underperformed with yields rising 28bps (97bps) to 5,14%. 10Y Bunds climbed 12bps (52bps) to 3,38%. 10Y Italian BTPs underperformed rising 9bps (87bps) to 4,42%, outperforming Bunds by -3bps.
10Y French OAT's underperformed rising 16bps (136bps) to 4,92%, underperforming Bunds by 4bps.
US High Yield (HY) Average Spread over Treasuries dropped -20bps (50bps) to 3,16%. US Investment Grade Average OAS dropped -6bps (12bps) to 0,96%.
Gold sold shed -4,6% (-10,1%) while Silver sold off by -6,1% (-32,0%). Major Gold Mines (GDX) sold off by -6,8% (-4,8%).
Goldman Sachs Commodity Index sold off by -2,4% (37,7%). WTI Crude sold off by -2,5% (54,2%).
Overnight in Asia…
S&P future -22 points; Hong Kong +0.8%; Nikkei -1.6%; China -0.5%
Asian shares slumped following Friday’s Wall Street selloff (Nvidia’s shares wiped out more than half a trillion dollars in market value last week) with investor appetite for the AI trade facing another test this week from Nvidia earnings and Anthropic expected IPO listing.
Iran targeted an air base in Bahrain in the first direct strike on the Gulf state in weeks, even as it reiterated that a path to ending the conflict with the US remained open. Tensions are still riding high over shipping in the SoH even as D. Trump indicated he was considering holding off on attacking Iran absent new provocations, according to a Reuters report.

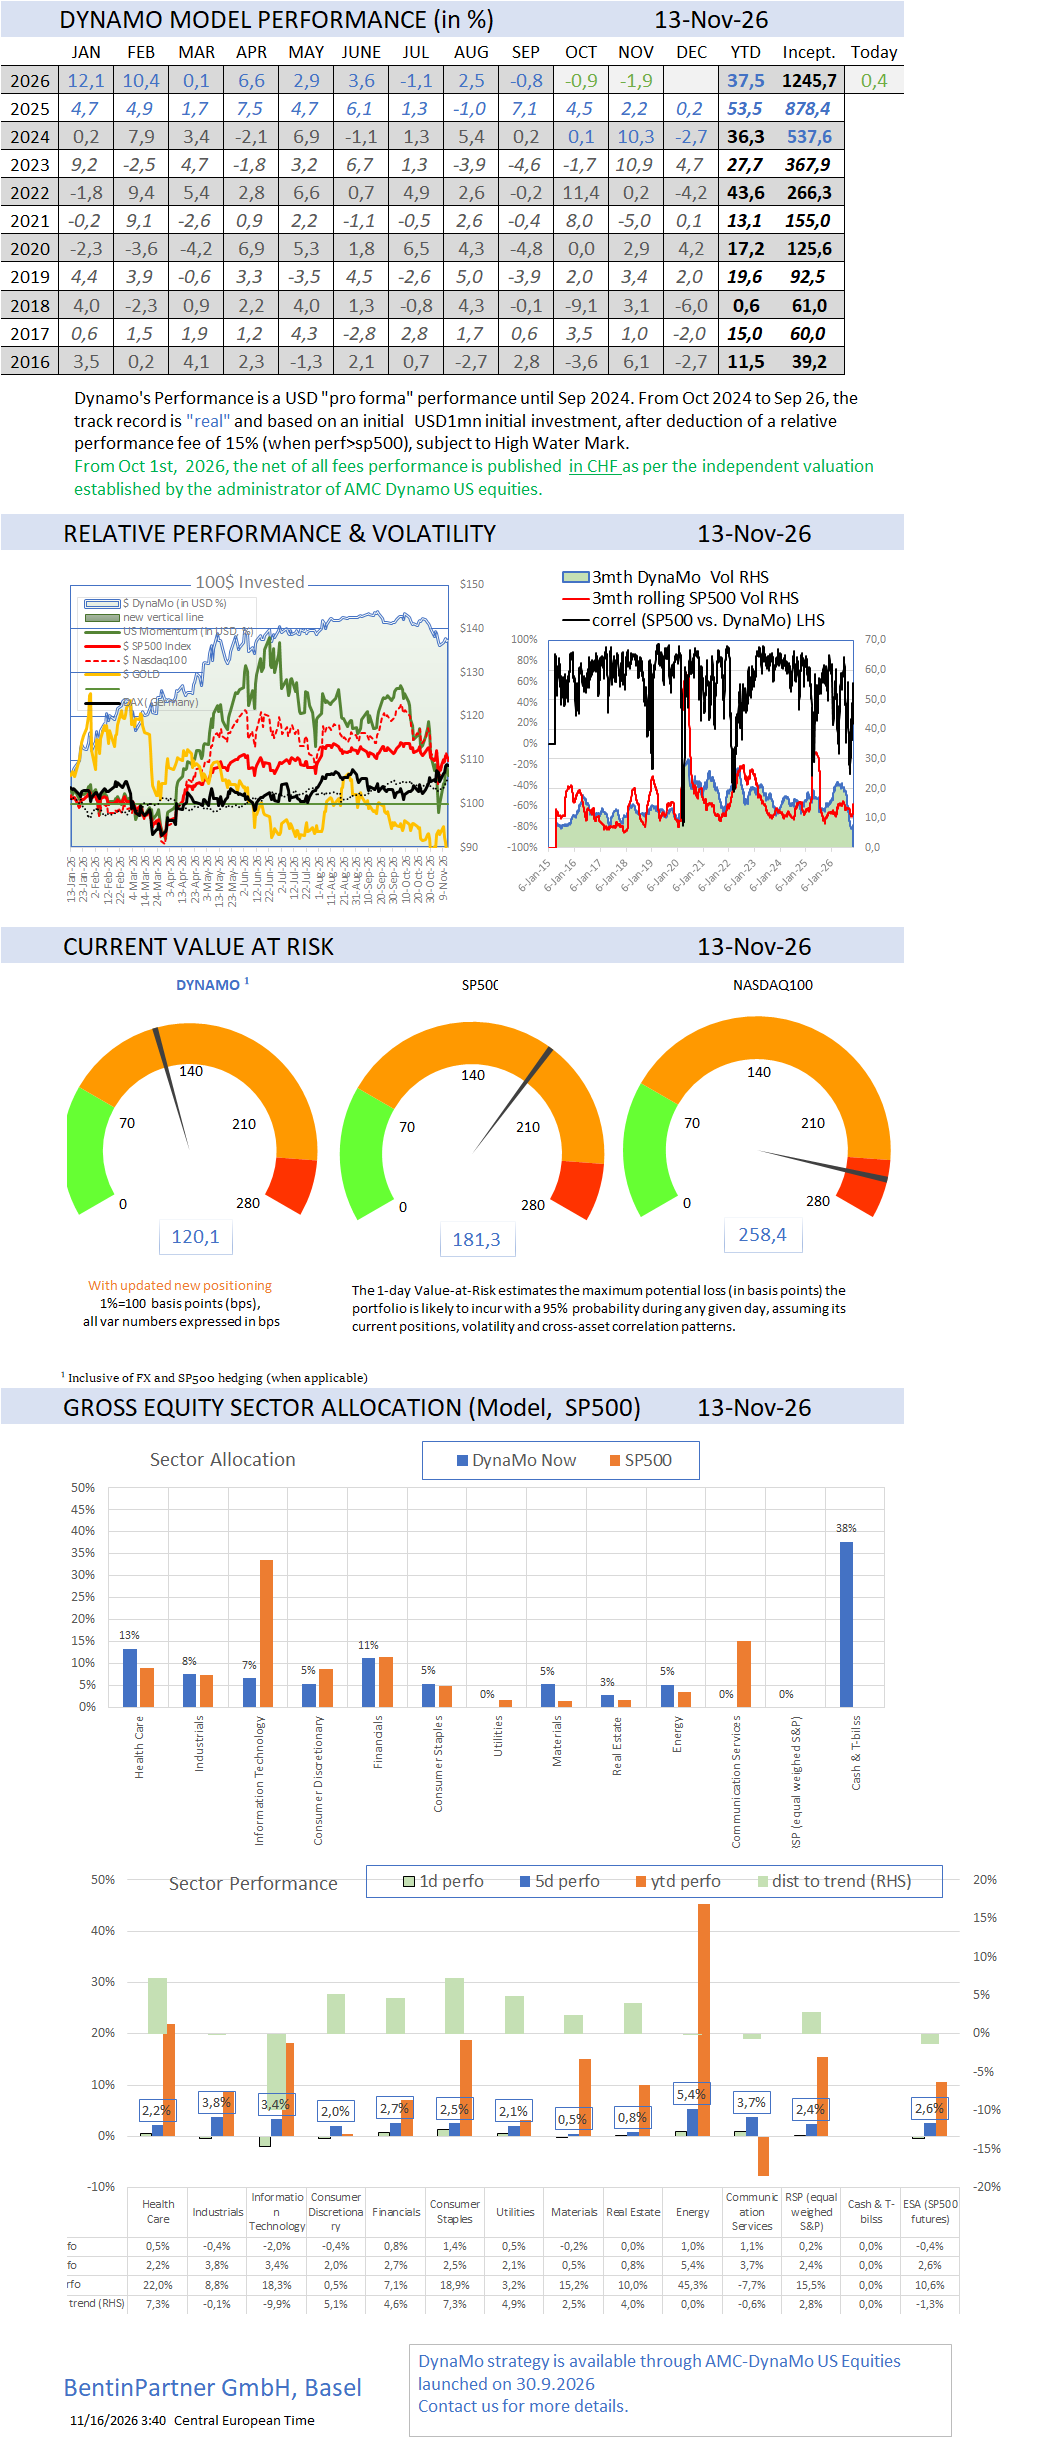
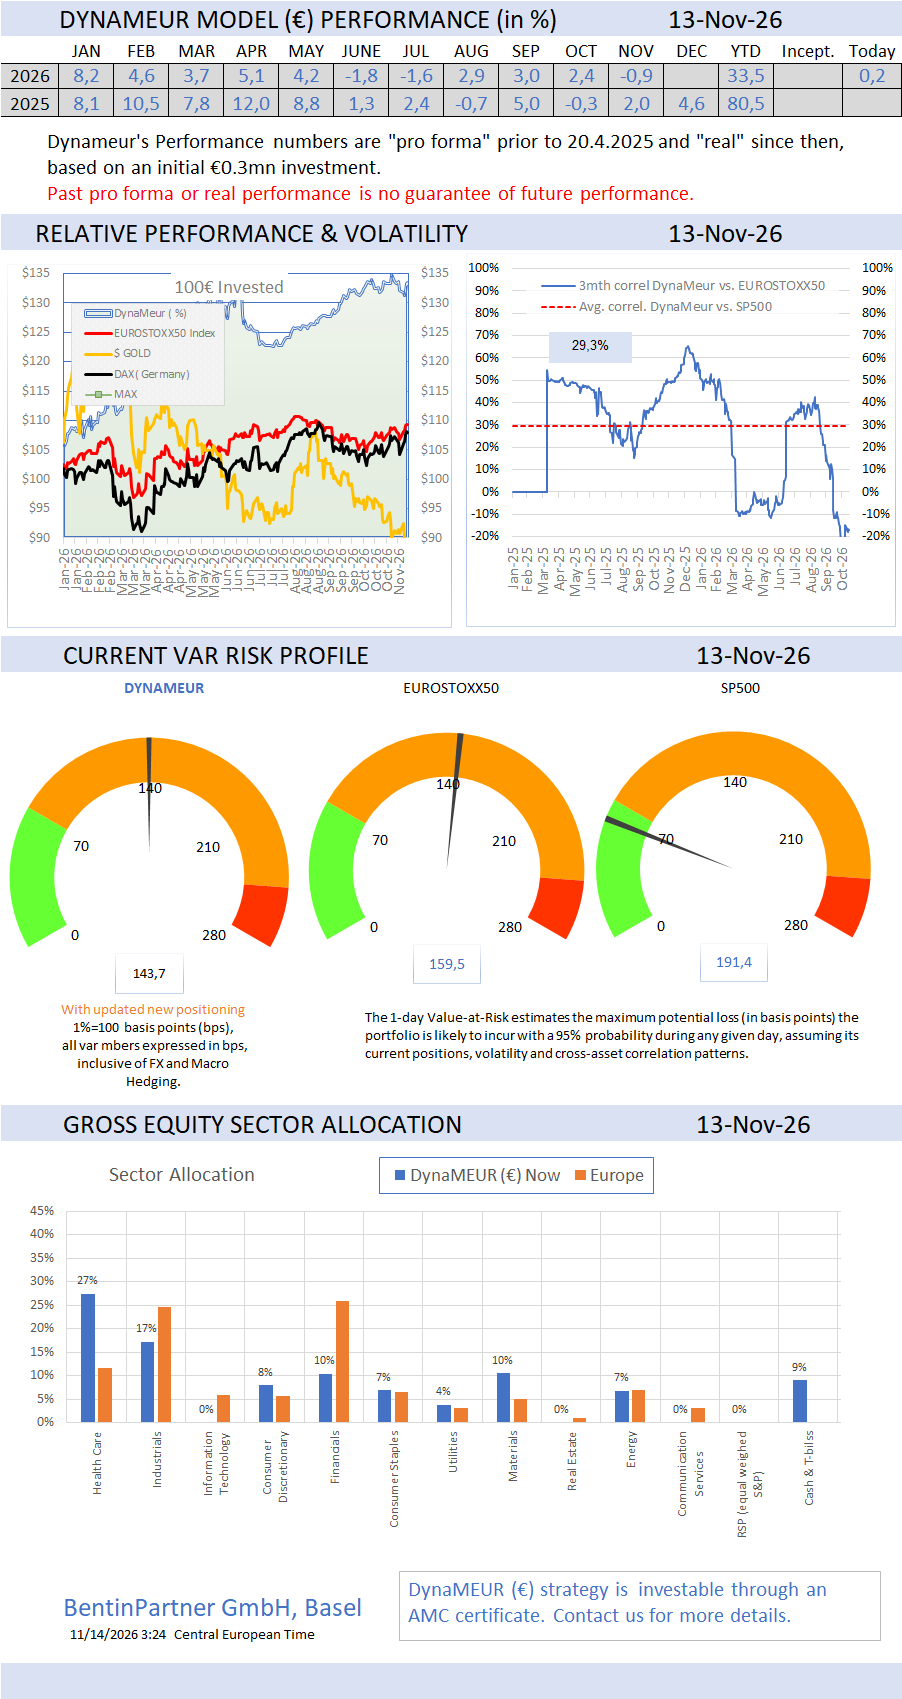
To learn more about our AMC offering and how to invest in the trend-following, visit our Advisory web page.
If you like our Weekly, you will love our Daily!
Consider a subscription today. Discounts may apply!
To learn more about us and how we can assist you, check our website
Important Disclaimer
© Copyright by BentinPartner LLC. This communication is provided for information purposes only and for the recipient's sole use. Please do not forward it without prior authorization. It is not intended as a recommendation, an offer, or solicitation for the purchase or sale of any security or underlying asset referenced herein or investment advice. Investors should seek financial advice regarding the suitability of any investment strategy based on their objectives, financial situation, investment horizon, and particular needs. This report does not include information tailored to any particular investor. It has been prepared without any regard to the specific investment objectives, financial situation, or particular needs of any person who receives this report. Accordingly, the opinions discussed in this report may not be suitable for all investors. You should not consider any of the content in this report as legal, tax, or financial advice. The data and analysis contained herein are provided "as is" and without warranty of any kind. BentinPartner LLC, its employees, or any third party shall not have any liability for any loss sustained by anyone who has relied on the information contained in any publication published by BentinPartner LLC. The content and views expressed in this report represent the opinions of Marc Bentin and should not be construed as a guarantee of performance with respect to any referenced sector. We remind you that past performance is not necessarily indicative of future results. Although BentinPartner LLC believes the information and content included in this report have been obtained from sources considered reliable, no representation or warranty, express or implied, is provided in relation to the accuracy, completeness, or reliability of such information. This Report is also not intended to be a complete statement or summary of the industries, markets, or developments referred to in the Report.

Comments